Builders Offer 5% Rates via Buydowns. FSBO Sellers Can Too
Builders Offer 5% Rates via Buydowns. FSBO Sellers Can Too
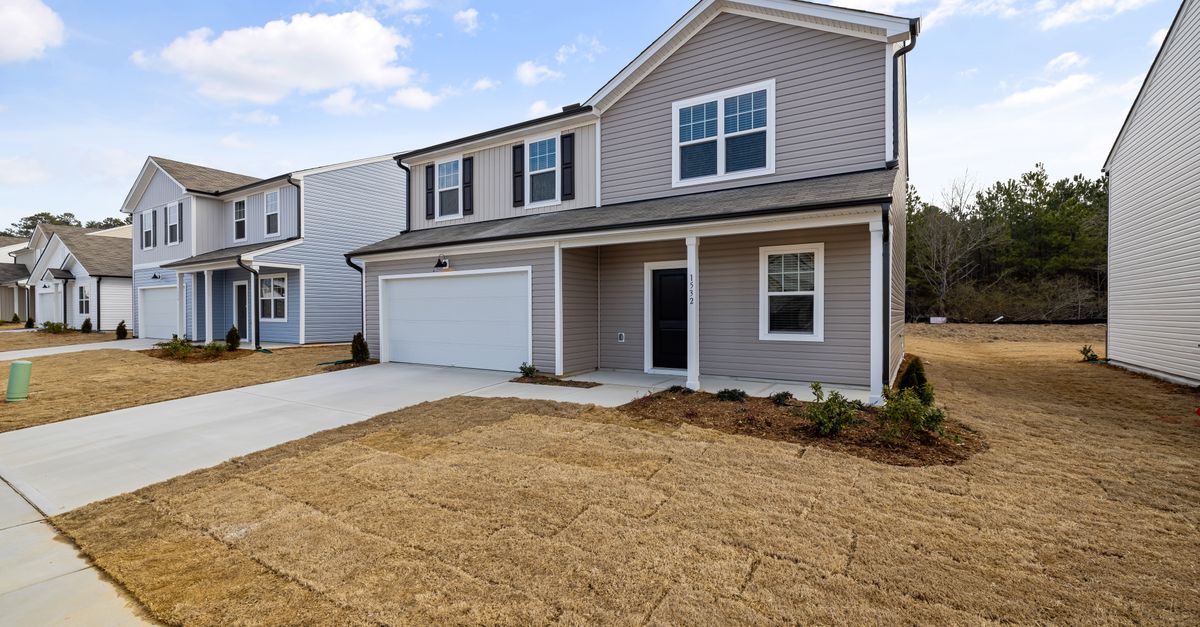
Your biggest competition this month isn't the house down the street. It's the builder down the road.
National builders are clearing spec inventory, and they're doing it by buying down mortgage rates, not by slashing prices. Permanent buydowns at 4.99% to 5.49%. 2-1 buydowns that drop a buyer into the fours in year one. Forward-commitment pools at 5.25%. Meanwhile the rest of America pays 7.40% for a 30-year fixed, per Freddie Mac's weekly survey. (Mortgage-Info.com, Oct 2026)
Do the math the way your buyer does it. At 5.49%, a $450,000 new build runs roughly $469 a month cheaper than the same purchase at market rates, per that same update. Builders are stacking $10,000 to $25,000 in closing credits on top. And the Mortgage Bankers Association says it's about to get more aggressive. New-home sales dropped 12% in September to the slowest pace since 2020, so deputy chief economist Joel Kan expects builders to sweeten incentives even further: rate buydowns, closing-cost assistance, upgrades. (New American Funding, Oct 15)
Your buyer compares payments, not prices
That's the uncomfortable part. When money costs 7.4%, a buyer doesn't compare your $420,000 resale to the builder's $450,000 new build. She compares the monthly payment. A brand-new house at 5.5% beats your five-year-old roof at 7.4%, even if your price is lower. The rate has become the product.
You can buy down a rate too
A buydown is just prepaid interest, and there's no rule that says only builders can offer one. A 2-1 buydown drops your buyer's rate about two points in year one and one point in year two, then settles at the market rate. At today's 7.40% that means roughly 5.4% in year one. A payment your buyer can actually live with. It costs you a few thousand at closing. Not forty. Not twenty.
Compare that to a listed sale, which hands roughly 6% of your price to agents. That's $24,000 on a $400,000 home. The commission you didn't pay is your weapons budget. Spend a few thousand buying down your buyer's rate instead of handing twenty-four thousand to a brokerage, and you'll still walk away with more equity than your neighbor with the agent sign out front.
And here's the trade-off most sellers miss. A $20,000 price cut saves the buyer a little interest over 30 years. A buydown saves them real money from month one, when the payment is what actually decides the deal. Sell the payment, not the discount.
How it works in practice
You don't wire anyone money at the kitchen table. The buydown goes through the buyer's lender as a seller concession. A credit on the closing statement, earmarked for the buydown. The loan officer structures it; your closing attorney or title company handles the paperwork. FHA, VA and conventional loans all allow seller concessions, and a standard buydown fits inside the usual limits. Just have your real estate attorney confirm the numbers for your state. Our state FSBO guides cover what's allowed where.
One piece of marketing advice: don't frame it as desperation. "New roof, great schools" is fine, but the line that books the showing is this: "Seller will buy down your rate to about 5.4% for the first year." Put the payment in the listing.
Builders are spending millions to sell payments instead of houses. You can sell a payment too, and you start with a $24,000 head start they don't have: the commission you never paid. Price the home fairly, offer the buydown, and be the listing your buyer remembers.
List for a free 15-day trial, then a one-time fee from $49. No commission, no agent. Want to see what 7.4% does to a buyer's monthly number? Run it through our mortgage calculator. And if you missed it, yesterday I wrote about showings dropping 20%. This is what sellers are up against, and this is how you answer it.
Sources: Mortgage-Info.com, October 2026; New American Funding / Freddie Mac / MBA, Oct 15 2026.